Quick Review: IRS transcript monitoring compares new tax-account activity with prior records to surface unfamiliar filings, income documents, refund events, and account changes. Alerts can support earlier action, but monitoring does not guarantee prevention or detection of every fraud event.
ACT NOW TO MONITOR IRS ACTIVITY BEFORE AN UNFAMILIAR FILING OR REFUND EVENT BECOMES A COSTLY SURPRISE.
A New Channel for Evaluating Tax Identity Protection
Tax identity fraud can be difficult to recognize because the warning signs often appear inside IRS records before they appear in a mailbox, bank account, or credit report. A taxpayer or business may not realize that a return, wage record, refund request, or account change is connected to their tax identity until the IRS rejects a legitimate filing or sends an unexpected notice.
IRS transcript monitoring gives taxpayers and businesses another way to evaluate account activity. By reviewing available IRS transcript data and comparing new information with previous records, tax security tools can help surface suspicious activity earlier. The process is designed to improve awareness and streamline the response, not to promise that every fraudulent event will be stopped.
The Problem: Tax Fraud Often Begins Outside Traditional Credit Monitoring
Traditional identity protection services generally focus on credit files, new accounts, loan applications, and other borrowing activity. Those services can be valuable for financial identity protection, but tax identity fraud may occur without any immediate change to a credit report.
A criminal using a stolen Social Security number may attempt to:
- File a fraudulent tax return
- Report wages or income that do not belong to the taxpayer
- Redirect a refund
- Submit an unauthorized tax form
- Change information associated with an IRS account
- Use a business tax ID in an unauthorized filing or transaction
These events may be visible through IRS records even when no new credit account has been opened. Without a tax-specific monitoring process, the taxpayer may discover the problem only after the damage has affected a refund, filing, balance, or tax deadline.
The Evidence: What IRS Transcripts Can Show
An IRS transcript is an official summary of tax information or account activity. The IRS provides several transcript types, each offering different information. The IRS explanation of tax transcripts describes the records taxpayers may request for personal and financial review.
Common transcript categories include:
- Return Transcript: Information from an originally filed tax return.
- Account Transcript: Account activity such as assessments, payments, penalties, adjustments, and notices.
- Wage and Income Transcript: Data reported to the IRS on forms such as W-2s and 1099s.
- Record of Account: A combined view of return and account information.
Tax security tools use authorized access to available IRS data and examine changes over time. IRS professionals may use systems such as the Transcript Delivery System to request transcript information. A monitoring service can then compare a current record with an earlier record and identify events that may require attention.
Potential indicators may include:
- An unfamiliar tax return posted to an account
- Wage or income information that does not match the taxpayer’s records
- An unexpected refund-related transaction
- A new balance, assessment, penalty, or adjustment
- An unfamiliar account change or authorization
- A tax event associated with a business that the owner does not recognize
- Activity suggesting an audit, lien, levy, or payment-plan change
Not every unusual transaction is fraud. An amended return, payroll correction, tax professional’s action, or legitimate business adjustment can also create a transcript change. The purpose of monitoring is to bring the event to the taxpayer’s attention so it can be reviewed promptly.

How Tax Security Tools Identify Suspicious Activity
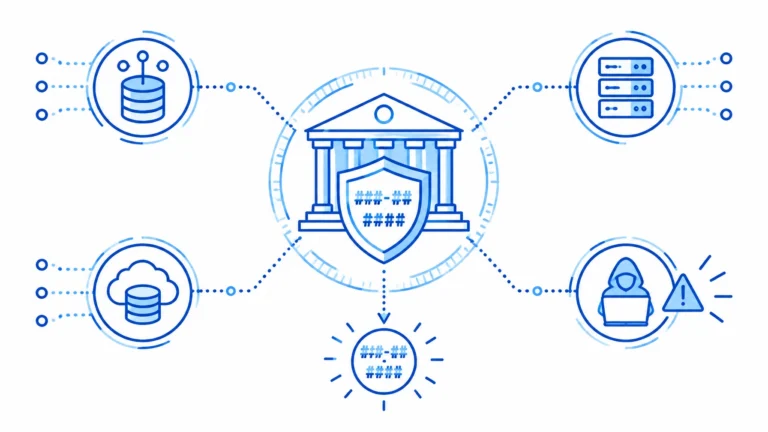
Tax security tools generally use a combination of scheduled data retrieval, change detection, rules, and alerts. The exact process differs by provider, authorization arrangement, account type, and available IRS data.
A typical workflow includes the following steps:
- Authorized account connection: The taxpayer, business, or authorized professional establishes access to the relevant tax information.
- Transcript retrieval: The service checks for updated records according to its monitoring process.
- Record comparison: New transcript information is compared with prior data or expected account activity.
- Event classification: The system categorizes changes, such as filing activity, income activity, refund activity, account adjustments, or enforcement indicators.
- Risk alert: The taxpayer or designated contact receives an email, text, dashboard notification, or other alert when a monitored event requires review.
- Human response: The recipient confirms whether the activity is legitimate and follows the appropriate IRS or professional process if it is not.
Some systems may also analyze transaction codes, dates, amounts, and account status indicators. These details can help organize a complicated transcript into a more understandable alert.
The important distinction is between monitoring and prevention. Monitoring can help identify a suspicious event sooner. It does not guarantee that a fraudulent filing will be blocked, that an identity thief will be identified, or that every IRS account change will be visible.
The Consequences: Why Earlier Awareness Matters
When suspicious tax activity goes unnoticed, the consequences can extend beyond a delayed refund. Individuals may need to verify their identity with the IRS, submit additional forms, correct inaccurate income records, or respond to notices that they did not expect.
Businesses may face additional complications, including:
- Disrupted payroll or information reporting
- Incorrect business tax balances
- Delayed refunds or credits
- Unauthorized changes to payment arrangements
- Audit or examination concerns
- Administrative costs and employee time spent investigating the issue
- Reputational concerns if customer or employee information is involved
Timing matters because tax records are connected to filing deadlines, payment schedules, payroll reporting, and refund processing. An alert does not resolve the issue by itself, but it can help the affected taxpayer begin verification and recovery steps before the problem becomes more difficult to correct.
The Prevention Framework: Build a Tax-Specific Monitoring Process
A practical tax identity protection process should combine monitoring with basic account security and careful review. Taxpayers and businesses can strengthen their approach by:
- Reviewing IRS account activity regularly
- Keeping copies of filed returns and supporting documents
- Confirming that W-2 and 1099 information is accurate
- Protecting Social Security numbers and employer identification numbers
- Limiting access to tax records and authorization documents
- Using strong, unique passwords and multifactor authentication where available
- Reviewing unexpected IRS notices promptly
- Confirming unfamiliar activity with a tax professional or the IRS
- Establishing a documented response plan for suspected fraud
Businesses should also define who receives alerts and who is authorized to investigate them. A clear process can reduce confusion when an alert arrives during a filing deadline or payroll cycle.
Taxpayers should not ignore an alert simply because the account balance or refund amount appears correct. Unauthorized activity may involve information that does not immediately create a financial loss, such as an unfamiliar income document or account authorization.
How Tax Guardian Supports Earlier Awareness
Tax Guardian is designed around tax identity activity rather than relying only on credit-report changes. Its service continuously monitors IRS accounts for suspicious activity and provides alerts intended to help taxpayers recognize unfamiliar events sooner.
Depending on the account and available information, monitored activity may include:
- Suspicious filing activity
- Unfamiliar wage or income records
- Refund-related events
- Potential Social Security number misuse
- Unexpected IRS account changes
Tax Guardian also provides recovery support for members who need help responding to a suspected tax identity issue. Details about the service are available on the Tax Guardian tax identity protection page, while the Why Tax Guardian page explains the company’s tax-specific approach.
Monitoring should be viewed as an early-warning layer. It works best when members review alerts, confirm whether activity is legitimate, and take appropriate action when a concern is identified. No monitoring service can guarantee prevention, complete visibility into every IRS event, or detection of every type of fraud.
A More Informed Approach to Tax Identity Security
IRS transcript monitoring can make tax-account activity easier to observe and investigate. By surfacing unfamiliar returns, income records, refund activity, and account changes, tax security tools help taxpayers and businesses move from passive discovery to earlier awareness.
Tax Guardian can help support that process through ongoing IRS account monitoring, instant alerts, and recovery assistance. Taxpayers and businesses can learn more about Tax Guardian and evaluate which level of protection fits their monitoring and support needs.
Frequently Asked Questions
1. What does IRS transcript monitoring detect?
IRS transcript monitoring can surface changes such as unfamiliar tax returns, unexpected wage or income records, refund-related transactions, assessments, penalties, account adjustments, and certain authorization or enforcement activity. The exact events visible to a monitoring service depend on the account type, authorization, IRS data availability, and the provider’s monitoring rules.
2. Does IRS transcript monitoring prevent tax identity theft?
No. Monitoring and alerts do not guarantee prevention. They are designed to support earlier awareness by identifying certain changes in available IRS records. A taxpayer must still review alerts and follow the appropriate IRS, tax professional, or identity recovery process when suspicious activity is found.
3. Can businesses use IRS transcript monitoring?
Yes. Businesses may use transcript monitoring to watch for certain changes involving business tax accounts, including assessments, balances, payment arrangements, liens, levies, and examination-related activity. The data available for a business account may differ from the information available for an individual taxpayer.
4. How does Tax Guardian respond to suspicious IRS activity?
Tax Guardian continuously monitors IRS accounts for suspicious activity and provides alerts when monitored events require attention. Its services also include recovery support designed to help members navigate tax identity issues. Monitoring results are not a guarantee that every fraudulent event will be detected or prevented.
Legal Disclaimer: This article is provided for general informational and educational purposes only. It is not tax, legal, financial, cybersecurity, or identity-theft-recovery advice, and it does not create a professional-client relationship. IRS transcript availability, monitoring scope, alerts, coverage, and recovery services may vary by account, plan, authorization, and applicable requirements. Readers should consult the IRS or a qualified tax, legal, or financial professional regarding their specific circumstances. Tax Guardian does not guarantee the prevention or detection of every fraudulent event.
Copyright © 2026 Tax Guardian. All rights reserved.